For food and beverage manufacturers looking to expand internationally, Europe can appear to be one large consumer market. Products move across borders, major retail groups operate in several countries and European consumers often follow similar trends. But when it comes to convenience retail, there is no single European market.
The way consumers buy a sandwich in London, an energy drink in Prague, a coffee in Amsterdam or a ready meal in Warsaw can involve very different retailers, wholesalers and distribution structures.
For international brands, this has an important consequence: a convenience store market entry strategy that works in one European country may fail completely in another.
The most effective approach is therefore to analyse Europe country by country and channel by channel. Manufacturers need to understand who controls retail access, whether distributors or wholesalers are required, how consumers use convenience stores, what commercial conditions retailers expect and which products fit specific consumption occasions.
Europe may be a single market in regulatory terms, but convenience retail remains remarkably local.
Why Does Convenience Store Market Entry Require Local Intelligence?
Convenience store market entry requires local intelligence because the structure of convenience retail differs significantly between European countries. The same product may need a supermarket buyer in one country, a wholesaler in another and a specialist distributor in a third.
The first mistake international food and beverage brands can make is defining the European convenience market by store size alone.
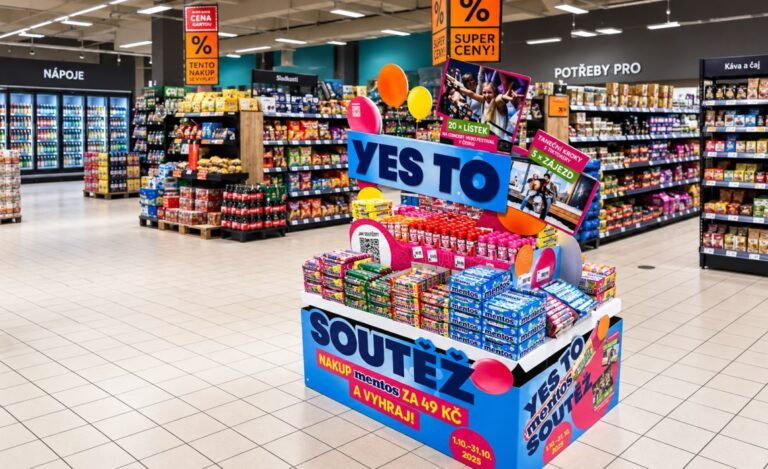
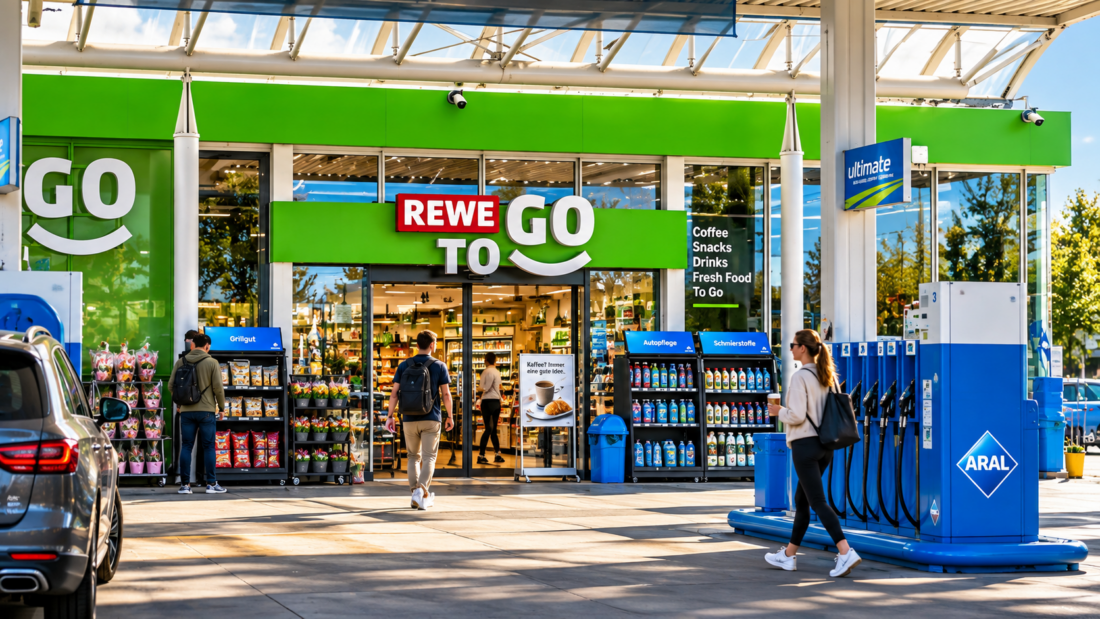
Convenience retail includes far more than traditional corner shops. Depending on the country, the channel can include petrol stations, railway station stores, neighbourhood supermarkets, kiosks, franchise networks, bakeries, urban food-to-go concepts, autonomous stores and thousands of independent retailers.
The decision about who gets space in the refrigerator or on the shelf can therefore be made by a national retailer, a wholesaler, a franchise organisation, a distributor or an individual shop owner.
This makes local convenience retail market intelligence an essential part of market entry. It should also form part of a wider European market entry strategy covering market selection, local partners, distribution channels and business expansion.
How Does the UK Convenience Store Market Work?
The UK convenience store market combines major grocery groups, symbol groups, wholesalers, forecourt operators and a large independent retail sector. It is one of Europe’s most developed convenience ecosystems, but this does not necessarily make it easy for an international brand to enter.
Major grocery groups operate convenience formats, while symbol groups, wholesalers, forecourt operators and independent stores create additional routes to market. A manufacturer therefore needs to understand not only which retailers to approach but also how wholesalers and distributors influence access to independent stores.
For a beverage or snack brand entering the UK convenience market, finding the right distributor may sometimes be more important initially than securing a meeting with a large supermarket buyer.
Food-to-go is another important part of British convenience retail. Meal deals, sandwiches, snacks, coffee, energy drinks and functional beverages compete for consumption occasions rather than simply traditional product categories.
This makes the UK particularly interesting for international brands that can clearly connect their product with an immediate consumer need such as breakfast, lunch, hydration, energy, snacking or food-to-go.
How Does Convenience Retail Work in the Czech Republic?
The Czech convenience store market combines organised grocery retail, petrol station networks, wholesalers and a substantial independent neighbourhood retail sector.
A particularly interesting feature is the role of Vietnamese entrepreneurs in Czech small-format retail. Over several decades, Vietnamese-owned stores have become an established part of neighbourhood shopping in many Czech towns and cities.
For international brands, this creates several possible routes to market: modern grocery chains, forecourt retail, wholesalers and independent convenience stores.
A successful food or beverage market entry strategy for the Czech Republic therefore needs to identify which channel best matches the product rather than simply approaching the largest retailers first.
This distinction is especially important for imported beverages, snacks and emerging consumer brands. A product designed for immediate consumption may require a different route to market from a premium speciality product or a brand intended for national supermarket distribution.
Why Is Poland an Important Convenience Retail Market?
Poland is particularly important for convenience retail because modern small-format stores have become deeply integrated into everyday shopping behaviour.
Żabka has developed a dense network of small-format stores built around proximity, food-to-go, beverages, digital services and frequent shopping occasions. Its development illustrates how convenience retail can become part of everyday urban infrastructure rather than merely a destination for emergency purchases.
For manufacturers, however, sophisticated convenience networks can also mean sophisticated buying requirements.
Products need a clear reason to occupy limited shelf or refrigerator space. Pricing, packaging, margins, promotional support, supply reliability and expected sales velocity all become important.
International manufacturers should therefore calculate the economics of retail entry before approaching buyers. Our analysis of convenience store listing costs, retailer margins and trade promotions explains why securing a listing is only one part of building a commercially sustainable convenience retail business.
The smaller the store, the harder every centimetre of shelf space has to work.
How Is the German Convenience Store Market Different?
Germany does not have one dominant convenience store model. Instead, convenience demand is distributed across petrol stations, supermarkets, travel retail, railway locations, kiosks, bakeries and newer urban food-to-go concepts.
This fragmentation can create opportunities for new products, but manufacturers need to define what they actually mean by entering the German convenience store market.
A premium functional drink targeting commuters may require a completely different distribution strategy from an imported beer aimed at kiosks or a snack product designed for petrol station stores.
Market segmentation therefore needs to come before retailer outreach.
For foreign companies, this also demonstrates why selecting a local market-entry partner should be based on channel expertise rather than general claims of market access. Different consultants, distributors and commercial partners may provide very different levels of access. Companies evaluating external support can use our overview of market entry agencies in Europe as a starting point for understanding the types of partners available.
What Makes the Netherlands Interesting for Convenience Brands?
The Netherlands is an interesting market for urban convenience, food-to-go and products built around specific consumption occasions.
Retailers are experimenting with urban store concepts, food-to-go, smaller formats and technology designed to make shopping faster. Convenience formats around transport hubs also demonstrate the importance of immediate consumption.
This creates opportunities for products designed around specific moments: breakfast, commuting, lunch, afternoon energy, post-work consumption and evening meals.
For manufacturers, understanding the consumption occasion can be just as important as understanding the product category.
A functional drink, premium snack or ready-to-eat product should therefore not only be positioned according to what it is. Manufacturers also need to define when, where and why a consumer should buy it.
How Is Technology Changing European Convenience Retail?
Convenience retail is increasingly becoming a technology-driven channel. Self-checkout, Scan & Go, digital loyalty programs, automated stores and AI-supported retail systems are changing how consumers shop and how retailers manage small-format stores.
These developments matter to manufacturers because technology can influence assortment decisions, consumer data, promotions and even which products perform well in very small retail environments.
The future convenience store may increasingly combine physical proximity with digital retail infrastructure.
For new brands, this could make data increasingly important. Retailers may expect stronger evidence of sales velocity, repeat purchasing, consumer engagement and promotional performance before allocating scarce shelf or refrigerator space.
What Can European Brands Learn From Taiwan’s Convenience Store Market?
Taiwan demonstrates how far convenience retail can develop when stores become integrated into consumers’ everyday lives.
Taiwan has one of the world’s most developed convenience store ecosystems, led by networks including 7-Eleven and FamilyMart. Stores provide far more than packaged food and drinks. They are deeply integrated into everyday life through meals, coffee, parcel services, payments and other services.
A beverage brand successful in Taiwanese convenience stores therefore operates within a very different retail ecosystem from one entering Germany or the UK.
The comparison provides an important lesson for Asian brands considering expansion into Europe: European market entry should not begin by copying the distribution strategy used at home.
Successful market entry begins not with the question “Where can we sell our product?” but “How does this market actually work?”
Is There a Single European Convenience Store Market Entry Strategy?
No. There is no single convenience store market entry strategy that works across Europe. Retail structures, distributors, wholesalers, consumer behaviour, price expectations and purchasing processes differ too significantly between countries.
International manufacturers should therefore resist the temptation to create one convenience strategy for Europe.
Instead, each target country should be evaluated according to its retail structure, major operators, wholesalers, distributors, consumer behaviour, price points, regulations, margins and relevant consumption occasions.
A practical convenience store market entry check should answer several questions before significant resources are committed:
- Who controls access to the convenience retail channel?
- Which retailers and store formats fit the product?
- Is a local importer, wholesaler or distributor required?
- What margins and listing conditions are typical?
- Which competing brands are already established?
- Which consumer occasion does the product address?
- Does pricing work throughout the distribution chain?
- What adaptations to packaging, positioning or product format may be necessary?
These questions also help determine whether a brand should enter a country directly, work with a distributor or build a broader local partnership network.
How Should Food and Beverage Brands Choose Their First European Market?
The best first European market is not necessarily the largest market. It is the country where product-market fit and route-to-market fit are strongest.
A manufacturer should compare consumer demand, competition, achievable retail pricing, distributor availability, retailer concentration, regulatory requirements and the cost of reaching customers before choosing a country.
This approach is particularly important for smaller international brands with limited market-entry budgets. Entering several countries simultaneously can spread commercial resources too thinly.
Instead, a brand can use one market to establish European references, test pricing, refine packaging and learn how distributors and retailers respond to the proposition before expanding further.
This principle applies beyond food and beverages. Our guide to how startups successfully enter international markets explores why phased expansion, local validation and partner selection can reduce the risks of entering unfamiliar markets.
What Can International Brands Learn From Successful Global Food Brands?
Market entry is not only about distribution. International consumer brands also need a proposition that consumers recognise and remember.
Successful food brands often combine a distinctive product with a strong origin story, recognisable packaging and consistent positioning. The global development of Tabasco provides an interesting example of how product identity and place of origin can support international brand recognition. Our analysis of the business behind Tabasco and Avery Island looks at the commercial story behind one of the world’s most recognisable hot sauces.
Sriracha provides a different lesson in brand development. Its international success illustrates how a product can move beyond its original consumer niche and become part of a much broader food culture. The business of Sriracha, branding and global growth demonstrates why distribution and brand identity need to develop together.
Regional consumer brands can also provide useful lessons. The development of Dristor Kebap from a local food business into a Romanian consumer growth story shows how concepts can evolve from local recognition toward wider commercial ambitions.
Think Country by Country, Channel by Channel
The central lesson for manufacturers is simple: Europe should be approached as a portfolio of local retail ecosystems rather than one uniform convenience market.
For food, beverage and consumer brands, European convenience retail offers considerable opportunities. Urbanisation, food-to-go, functional beverages, smaller households and demand for faster shopping are creating new consumption occasions.
But opportunity does not eliminate complexity.
The UK, Czech Republic, Poland, Germany and the Netherlands demonstrate that convenience retail can mean something different only a few hundred kilometres across a border. Taiwan provides an even stronger comparison of how deeply local retail ecosystems can shape market access.
For manufacturers planning international expansion, the conclusion is straightforward: think country by country, channel by channel and retailer by retailer.
That is where a successful convenience store market entry strategy begins.
ABOUT THE EXPERT
Tobias W. Loitsch
Tobias W. Loitsch works with manufacturers and product brands looking to bring their products into new international markets. From identifying the right markets and distribution partners to developing routes to market and opening access to retailers and convenience store networks, he supports companies in turning international expansion opportunities into viable sales channels across Europe and Asia.
Further Market Entry Insights
- Convenience Store Listing Costs: Fees, Margins and Trade Promotions
- European Market Entry: Strategies, Partners and Business Expansion Guide
- Best Agencies for Market Entry in Europe
- How Startups Successfully Enter International Markets
- Inside Avery Island: The Business Behind the World’s Most Famous Hot Sauce
- The Business of Sriracha: Branding, Growth and Global Success
- From Local Kebab Shop to Investment Story: How Dristor Kebap Is Building Romania’s Next Consumer Brand